All articles · 2026-03-15 · General
Bullseye in Leuven: Lyff. brings financial clarity to Medica
Three darts for financial clarity. Discover how Lyff. helped the new generation of medical professionals sharpen their future during Medica in Leuven.
By Jan Hermans, CEO & founder of Lyff.
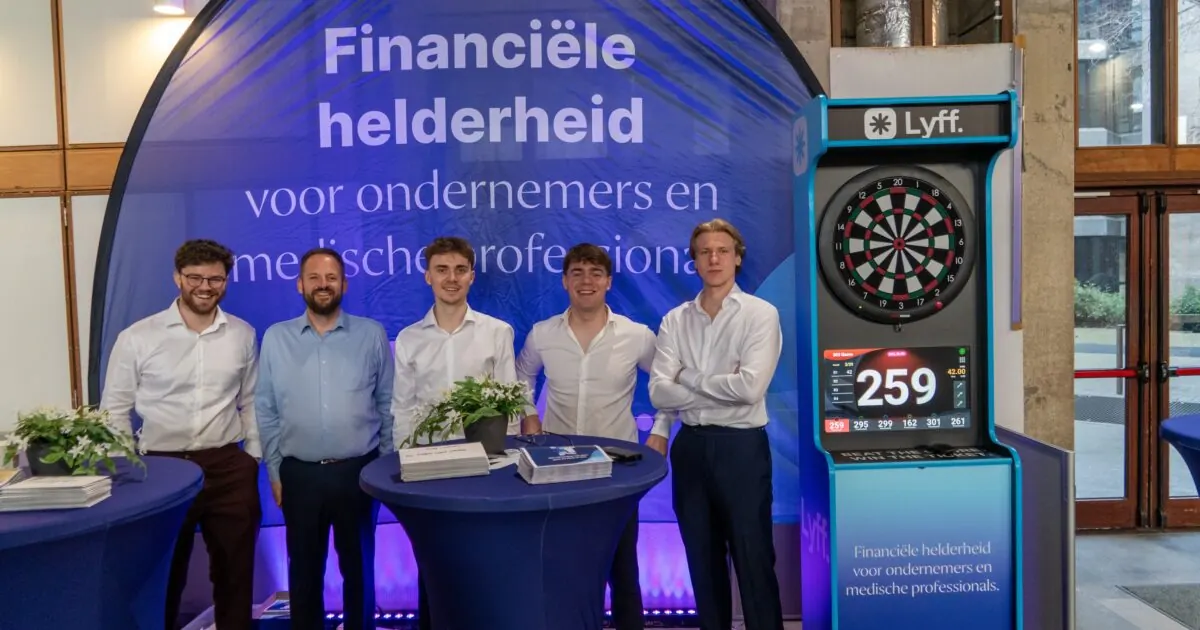
The challenge: 3 darts
The rules were simple: everyone got three darts to prove their focus. The competition among the students was palpable, and the atmosphere was immediately vibrant. The bar was set high, but in the end, the scoreboard settled on an impressive top score of 108.
The control room of the medical entrepreneur
During the Medica evening in Leuven, we noticed that many students and young doctors primarily view their management company (managementvennootschap) as a fiscal necessity. But as I write in my book Fiscal Shortcuts for Management Companies, your company is much more than that. It's a shoebox with taps. You decide which tap to open: remuneration, dividend, or pension accrual. Especially for doctors, that last tap is crucial, because the statutory pension for self-employed individuals often isn't enough to maintain your standard of living.
Take the RIZIV contract. Many contracted healthcare providers (geconventioneerde zorgverleners) receive an annual allowance, but forget that this instrument can be perfectly combined with an individual pension commitment (IPT). By correctly setting your salary as an anchor point, you increase the scope within the 80-percent rule. This way, you build capital with gross money from the company that later makes the difference between merely getting by and true financial freedom.
Real estate as a leverage without private stress
One of the most powerful shortcuts for the medical professional is linking your pension plan to real estate. Instead of privately repaying a loan with net pots from which 50 percent tax has already been deducted, you can use your IPT for a bullet loan. You then only pay the interest privately, while you make the capital repayment with tax-deductible premiums in your company. At Lyff., we call this smart real estate financing.
Imagine: you buy a practice building for 300,000 euros. With a classic credit, this would cost your company gross more than a million euros over twenty years. Through an IPT structure, you quickly save hundreds of thousands of euros because you build your assets with gross money. That is the essence of fiscal optimization that we work on every day.
Do you want to know which mechanisms from my book can also make a difference for your practice? You can read more about our approach to remuneration optimization here or order a copy of my book directly.
Frequently asked questions
Why is an IPT more interesting than merely distributing dividends?
A dividend simply moves money from your company to private and does not count towards your pension accrual. An IPT premium, on the other hand, is a deductible business expense that directly strengthens your pension reserve and creates new fiscal space for future projects, such as real estate.
Can I freely invest my RIZIV allowance?
The RIZIV allowance is a social benefit that must be deposited into a specific contract. Although you are bound by certain solidarity guarantees, you can often choose unit-linked funds (tak 23-fondsen) within that structure to generate more returns than with a classic savings account.